

 Call Us



In most cases, PMP certification costs are tax deductible only if you are self-employed or run your own business, where the exam fee, training course and PMI membership can be claimed as ordinary business expenses on Schedule C. Most salaried, W-2 employees in the United States lost this deduction when the Tax Cuts and Jobs Act suspended unreimbursed employee expenses, and that suspension was made permanent by the One Big Beautiful Bill Act in 2025. Employees who still want a tax-advantaged path generally have to route the cost through an employer's Section 127 educational assistance plan rather than claim it directly on their own return. This guide breaks down exactly what applies to your situation, whether you are self-employed, salaried, or based outside the US.
Key Highlights: Is PMP Certification Tax Deductible in 2026?
- Self-employed professionals and independent contractors filing Schedule C can generally deduct PMP exam fees, prep courses, PMI membership dues and related travel as ordinary and necessary business expenses.
- W-2 employees cannot deduct unreimbursed certification costs on their federal return for 2026 because the Tax Cuts and Jobs Act suspended this miscellaneous itemized deduction from 2018 through 2025, and the One Big Beautiful Bill Act passed in 2025 made that suspension permanent.
- The main exceptions that still allow a W-2 deduction are armed forces reservists, qualified performing artists and certain fee-basis government officials.
- A Section 127 employer educational assistance programme lets an employer reimburse up to 5,250 US dollars per employee per year tax free, and this cap stays at 5,250 US dollars through 2026 before it becomes inflation-indexed.
- The Lifetime Learning Credit usually does not apply to standalone PMP exam fees or non-degree prep courses because it requires payment to an eligible Title IV educational institution, which most PMP training providers are not.
- Whether the education "qualifies you for a new trade or business" is the test that most frequently disqualifies a deduction, and PMP certification for an existing project manager generally passes this test while it can fail for someone changing careers into project management.
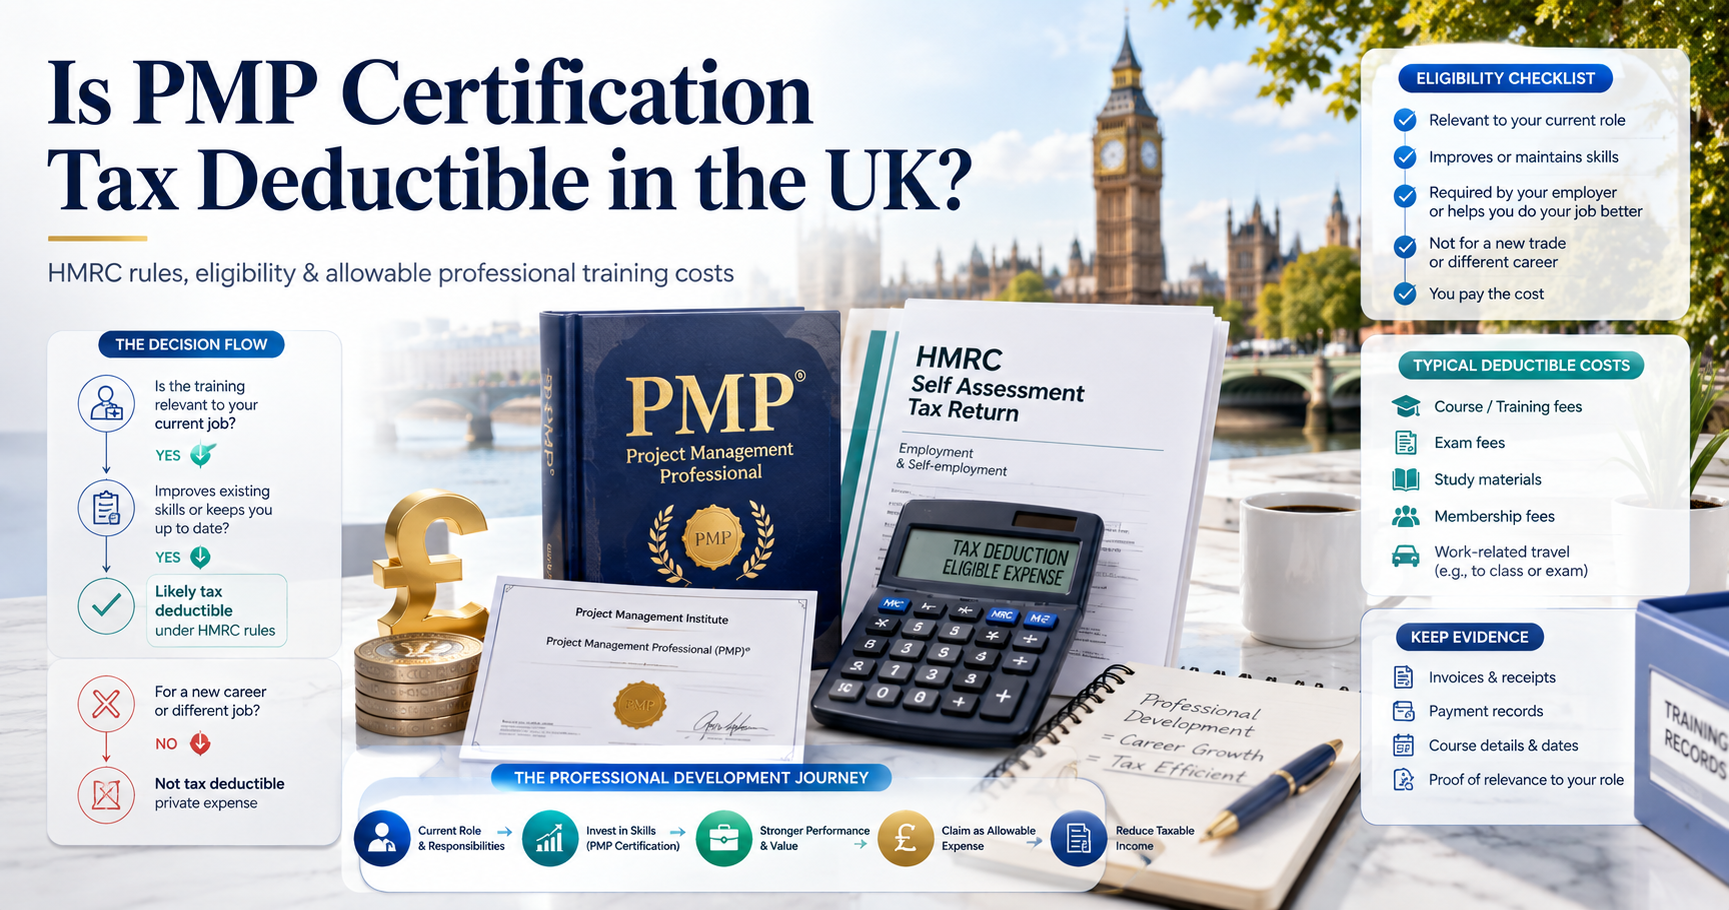
- UK-based professionals may be able to claim tax relief on PMI membership subscriptions through HMRC's List 3 of approved professional bodies, or as a self-assessment business expense if self-employed.
Who Can Actually Deduct PMP Certification Costs in 2026?
Whether a PMP certification expense is deductible depends almost entirely on how you earn your income, not on the certification itself. The Internal Revenue Service treats the PMP exam fee, prep course tuition and PMI membership dues as work-related education expenses, and it applies the same two-part test it applies to any professional development spending: the education must maintain or improve skills required in your present work, or be required by your employer or by law to keep your current salary, status or job, and it must not be part of a programme that qualifies you for a new trade or business.
For a working project manager who is adding the PMP credential to validate skills already used on the job, that test is usually satisfied. The complication is not whether the expense qualifies as work-related education. It is whether your filing status even allows you to claim work-related education as a deduction at all, and that is where self-employed professionals and W-2 employees diverge sharply.
If You Are Self-Employed: Deducting PMP Costs on Schedule C
Independent project management consultants, freelancers and small business owners who file Schedule C are in the best position to deduct PMP certification costs. If the certification maintains or improves skills used in your existing consulting or contracting work, the exam fee, an exam prep course, study guides, PMI annual membership and reasonable travel to a testing centre can typically be reported as a business expense under Other Expenses in Part V of Schedule C, often labelled something like Professional Development or Continuing Education.
Anyone weighing the full out-of-pocket cost before committing should first work through the complete PMP certification cost breakdown, which separates the PMI exam fee from training costs, since only the portions actually paid and substantiated with receipts can be deducted.
What Qualifies as a Deductible Expense
The categories that self-employed candidates most commonly deduct include the following.
Expense Type | Typically Deductible for Schedule C Filers |
|---|---|
| PMI membership dues | Yes, as a professional organisation membership expense |
| PMP exam application and exam fee | Yes, if the certification relates to your current line of work |
| Exam prep course or bootcamp tuition | Yes, reported as continuing education or professional development |
| Study guides, practice exams and simulators | Yes, as ordinary supplies for the education |
| Retake exam fee | Yes, on the same basis as the original exam fee |
| Travel to an in-person testing centre or classroom | Yes, mileage, parking or airfare tied directly to the education |
| PDU-earning courses for the 3-year renewal cycle | Yes, since they maintain an existing credential rather than create a new one |
The New Trade or Business Test That Trips People Up
The rule that most frequently disqualifies a PMP deduction has nothing to do with the certification's cost or content. It is whether the education qualifies you for a new trade or business. The IRS applies this test literally: education that would let someone move into a new profession is not deductible even if the person never actually changes jobs. A bookkeeper studying for the CPA exam cannot deduct the cost because passing opens up an entirely new credentialed profession, even if she stays at the same firm afterward.
Applied to project management, an established project coordinator, program lead or technical lead who is already performing project management duties and adds the PMP to formalise and validate that existing role generally clears this test, since the certification maintains and improves skills already in use. Someone with no project management background who is using the PMP purely as an entry ticket into a brand-new career is on much shakier ground, and that distinction is worth discussing with a tax professional before assuming a deduction applies.
If You Are a W-2 Employee: Why the Rules Changed
Before 2018, a salaried employee could deduct unreimbursed work-related education expenses, including certification exam fees and professional dues, as a miscellaneous itemized deduction once total miscellaneous deductions exceeded 2% of adjusted gross income. The Tax Cuts and Jobs Act of 2017 suspended that entire category of deduction for tax years 2018 through 2025.
Rather than expiring on schedule and reverting to the old rules, the suspension was made permanent for most W-2 employees by the One Big Beautiful Bill Act, which was signed into law in 2025. Practically, this means a salaried project manager paying for a PMP exam fee, prep course or PMI dues out of pocket in 2026 cannot deduct that cost on a federal return, no matter how clearly it relates to their current job.
The Narrow Exceptions That Still Apply
A small number of W-2 workers retained the ability to deduct unreimbursed employee expenses even after the Tax Cuts and Jobs Act. These are armed forces reservists travelling more than 100 miles from home for training, qualified performing artists meeting specific income thresholds, and fee-basis state or local government officials. Outside those categories, a salaried employee who wants a tax-advantaged path to PMP certification needs to look at what the employer can do rather than what can be claimed individually.
The Practical Workaround: Section 127 Employer Educational Assistance
Section 127 of the Internal Revenue Code allows an employer to reimburse an employee up to 5,250 US dollars per calendar year for qualifying education expenses, including certification exam fees, tuition and required materials, and the employee owes no federal income tax or payroll tax on that reimbursement. The employer, in turn, can deduct the reimbursed amount as a business expense.
This cap has held at 5,250 US dollars through 2025 and 2026, with inflation indexing due to begin after 2026, and it requires a written educational assistance plan that meets IRS nondiscrimination rules rather than an informal, case-by-case reimbursement.
This is the route most tax advisers now point salaried employees toward, since it sidesteps the individual deduction question entirely. It is also where the employer's decision-making matters most. An L&D or PMO manager who is planning certification budgets for several team members at once, rather than reimbursing one exam fee at a time, typically gets more favourable per-seat pricing and a cleaner audit trail by working through Simpliaxis's corporate and group training programme, which is built around exactly this kind of organisation-funded enrolment rather than individual, ad hoc purchases.
Employees who are self-funding in the absence of an employer plan, and who are choosing a course on their own, can compare formats and pricing directly on the PMP certification training course page before deciding how to structure the purchase for the tax year.
Does the Lifetime Learning Credit Cover PMP Training?
The Lifetime Learning Credit is frequently mentioned in online discussions of certification costs, and it is worth being precise about where it does and does not apply. The credit is worth up to 2,000 US dollars per tax return and phases out for single filers with modified adjusted gross income between 80,000 and 90,000 US dollars, and for joint filers between 160,000 and 180,000 US dollars, thresholds that have been unchanged since 2020. The credit applies to qualified tuition and required fees paid to an eligible educational institution, defined by the IRS as one that participates in federal student aid programmes and is generally accredited to award degrees or other recognised credentials.
This is the detail most general certification-tax articles gloss over. A standalone PMP exam fee paid to PMI, or a prep course run by a training provider that is not a degree-granting, Title IV eligible institution, typically will not generate the Form 1098-T needed to claim the Lifetime Learning Credit. The credit is far more likely to apply if PMP-adjacent coursework is taken through an accredited university's continuing education division that issues that form. Before assuming this credit offsets a PMP training purchase, confirm with the training provider whether they are a Title IV institution, since most dedicated certification training companies are not.
Is Your PMI Membership Fee Deductible?
PMI membership dues follow the same self-employed versus W-2 split as the exam and training costs. A self-employed consultant can generally deduct PMI membership as a professional organisation dues expense, provided PMI's main purpose is professional development rather than entertainment or lobbying activity that would make dues non-deductible. A W-2 employee, under current law, cannot deduct that same membership fee as an unreimbursed employee expense. Since renewal costs, including the CCR system fee, PDU-related spending and membership, recur every three-year cycle, it is worth reviewing the full PMP certification renewal fee structure alongside your tax situation so the deductible and non-deductible pieces of your ongoing costs are clear before the cycle resets.
What About Outside the US? UK Tax Relief on PMI Subscriptions
Tax treatment outside the United States follows different rules entirely. In the United Kingdom, HMRC maintains a List 3 of approved professional bodies and learned societies whose membership subscriptions qualify for tax relief when membership is relevant to the individual's employment. An employed UK project manager should check the current List 3 to confirm PMI's inclusion before claiming relief, since approved-body lists are updated periodically. Where a subscription qualifies, relief is given at the claimant's marginal income tax rate, so a basic-rate taxpayer effectively recovers 20% of the subscription cost and a higher-rate taxpayer recovers 40%. Self-employed UK professionals instead claim PMP-related training and membership costs as an allowable business expense on the self-assessment return, following the same wholly-and-exclusively-for-the-business standard that applies to any other business cost.
How to Document and Claim Your PMP Deduction
Whatever category you fall into, the documentation habits are the same. Keep the PMI receipt for the exam application and fee, the invoice from your training provider, PMI membership renewal confirmations, and any travel receipts tied directly to the exam or the course. If you are self-employed, these support the Schedule C entry. If your employer is reimbursing you under a Section 127 plan, keep copies of the plan document and the reimbursement request in case of an audit of either your return or the employer's plan.
- Confirm your filing status first. Determine whether you are filing as self-employed, a W-2 employee, or a mix of both, since this alone decides which path is available.
- Separate exam fees from training fees. Keep the PMI exam receipt and the training provider invoice as distinct line items rather than one lump sum.
- Ask about a Section 127 plan before you pay. If you are salaried, check with HR whether a written educational assistance plan already exists, since reimbursement is only tax free if it is paid through that structure.
- Verify institution eligibility for education credits. Before assuming the Lifetime Learning Credit applies, confirm the training provider issues Form 1098-T.
- Talk to a tax professional about the new-trade-or-business test. This is the single most common reason a certification deduction gets disallowed on review.
A Quick Decision Table: Your Status vs Your Options
Your Situation | Primary Option | Typical Outcome |
|---|---|---|
| Self-employed or Schedule C filer | Deduct exam fee, course and PMI dues as a business expense | Usually fully deductible if the new-trade-or-business test is passed |
| W-2 employee, employer offers a Section 127 plan | Route the cost through employer reimbursement | Up to 5,250 US dollars per year received tax free |
| W-2 employee, no employer assistance plan | Pay out of pocket | Generally not deductible on the federal return for 2026 |
| Armed forces reservist, performing artist or fee-basis official | Claim as an unreimbursed employee expense | Deduction still permitted under the narrow statutory exception |
| UK employee | Claim relief on PMI subscription if approved under HMRC List 3 | Relief given at marginal tax rate, subject to confirming List 3 status |
| UK self-employed | Claim as an allowable business expense on self-assessment | Deductible if wholly and exclusively for the business |
Why This Matters More When an Employer Is Funding the Certification
The tax question changes shape entirely once certification spending moves from an individual decision to a team or department budget. An L&D manager sponsoring PMP certification for five or ten staff at once is not filing a Schedule C or chasing a Lifetime Learning Credit threshold. They are structuring a written educational assistance programme that keeps every employee's reimbursement under the Section 127 cap, and negotiating group pricing rather than paying retail per-seat rates. Reviewing current PMP salary and career-impact data alongside the tax treatment gives a sponsor a cleaner business case, since the combination of a tax-free benefit for staff and a deductible expense for the organisation is generally more attractive to finance teams than reimbursing certification costs ad hoc.
Conclusion
PMP certification costs are not automatically tax deductible for everyone, and the single biggest factor is not the certification itself but how you are employed. Self-employed professionals have a reasonably clear path to deducting the exam fee, training and PMI dues as ordinary business expenses, provided the certification maintains rather than creates a new trade or business. Salaried W-2 employees, by contrast, lost the ability to claim these costs directly once the Tax Cuts and Jobs Act suspension of unreimbursed employee expenses was made permanent by the One Big Beautiful Bill Act, which leaves an employer-funded Section 127 plan as the most reliable tax-advantaged route.
The Lifetime Learning Credit, despite being widely mentioned online, usually does not apply to standalone exam fees or non-degree prep courses because it depends on payment to a Title IV eligible institution. None of this changes what the PMP credential is worth in the job market, but it does change how the true after-tax cost of earning it should be calculated, and that calculation looks different depending on whether you are paying for yourself or an employer is footing the bill.


 Lowest-Price Challenge







 Personalized Path


.webp)


 USA
 Canada
 India
 UK
 Australia
 Singapore


